
Compliance teams buying AML software in 2026 are choosing between platforms that look nearly identical on a vendor call and behave very differently once they’re processing your actual transaction volume. The feature lists overlap. The marketing language overlaps even more. What separates a tool that holds up from one that generates six months of false positives and investigator burnout is almost never visible in a demo. It shows up in production, usually after the contract is signed.
This article isn’t a ranked list of products. It’s a framework for sorting AML tool categories by what they’re actually built to do, so you can match a platform to your transaction volume, risk profile, and existing stack before you commit budget and a year of integration work to the wrong one.
What’s actually different about AML tooling going into 2026
The baseline has moved. Rules-based monitoring alone no longer satisfies most regulators or most risk committees, and the reasons why static rules miss layered laundering patterns have been covered in detail elsewhere, including in a piece on why machine learning catches what static AML rules miss. What matters for a buying decision right now is that nearly every vendor in this space now claims some form of machine learning detection, which means the claim itself has stopped being a useful differentiator.
The real differences in 2026 show up in three places: how a platform handles alert volume at scale, how cleanly it integrates with the KYC and case management systems you already run, and how much tuning it needs before the false positive rate becomes workable. A platform that performs well in a vendor’s reference case with a mid-sized bank may behave entirely differently against a fintech’s transaction patterns, especially if your customer base skews toward higher-velocity, lower-ticket transactions.
Another shift worth naming: more buyers are now evaluating transaction monitoring, sanctions screening, and case management as separate purchasing decisions rather than assuming one vendor’s end-to-end suite covers all three well. That’s the structure this article follows, because it’s increasingly how procurement actually happens.
Transaction monitoring platforms built for high-volume fintechs
Transaction monitoring is the category most compliance leads think of first, and it’s the one where volume matters more than almost any other factor. A platform tuned for a regional bank processing a few thousand transactions a day will choke, functionally or financially, on a payments fintech processing millions.
When shortlisting transaction monitoring platforms, weigh them against these factors rather than feature checklists:
- Throughput under real load. Ask for performance benchmarks at your actual or projected transaction volume, not the vendor’s largest reference client.
- Model retraining cadence. Static models decay as laundering typologies shift. Ask how often detection models retrain and whether that retraining requires a vendor services engagement or happens on your own schedule.
- Alert tuning control. Some platforms let your compliance team adjust thresholds and rules directly; others require a vendor ticket for every change. The second model slows you down every time your risk profile shifts.
- Explainability. Regulators increasingly expect you to explain why a model flagged or cleared a transaction. A platform that can’t produce a readable rationale for an alert creates a problem at exam time, not just at implementation.
For fintechs processing high transaction volumes with thin margins per transaction, the cost of a platform’s false positive rate often outweighs its licensing cost. Every false positive is an investigator hour. A platform priced lower but generating twice the noise can cost more within a year.
Sanctions and watchlist screening tools worth shortlisting
Sanctions screening is often bundled into transaction monitoring suites, but it’s worth evaluating separately because the failure modes are different. A transaction monitoring miss usually means a suspicious pattern goes unflagged. A sanctions screening miss can mean processing a transaction for a sanctioned entity directly, which carries a different order of regulatory consequence.
The questions that matter here:
- List coverage and update frequency. Confirm which sanctions lists the tool screens against (OFAC, UN, EU, UK, and relevant regional lists) and how quickly updates propagate after a list changes.
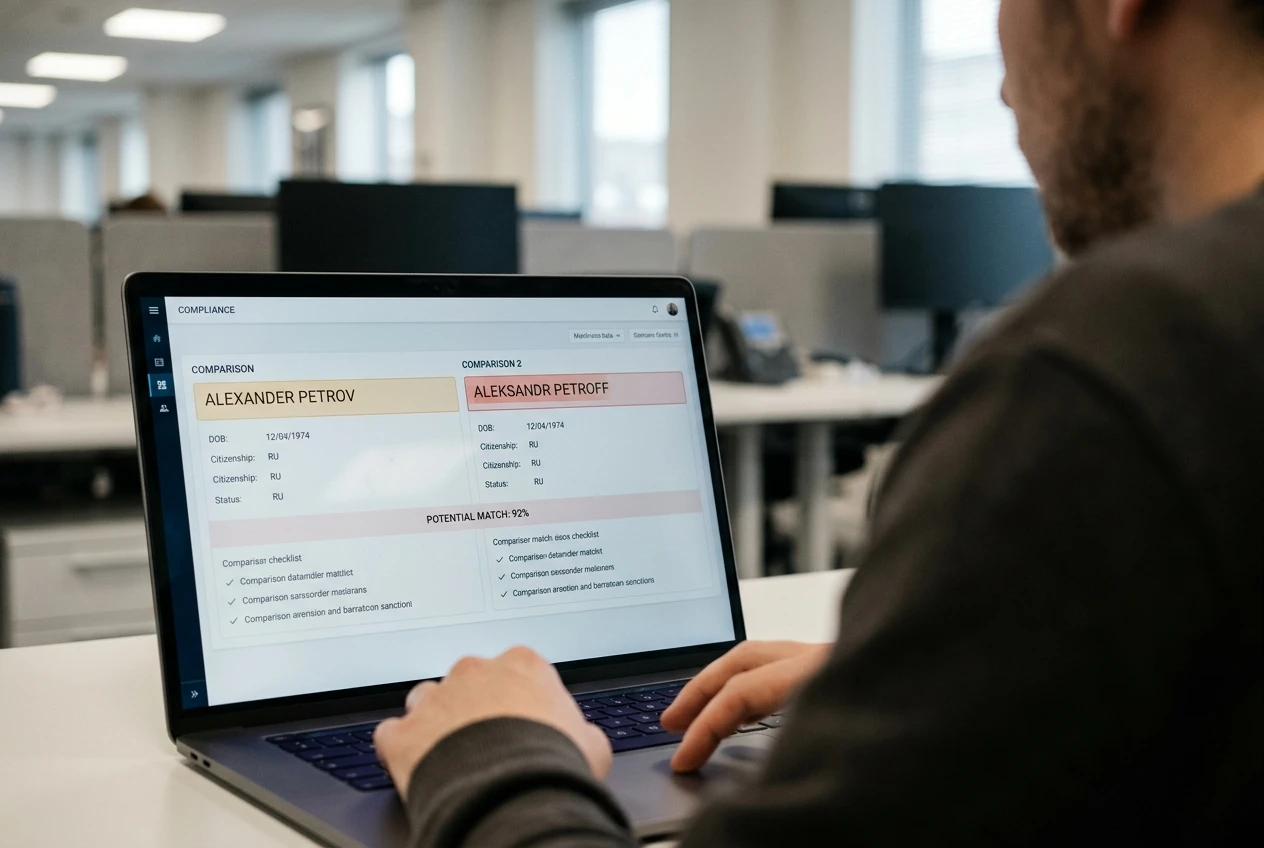
- Fuzzy matching quality. Name variations, transliteration, and partial matches are where screening tools genuinely differ. Ask for a live test against known difficult name pairs rather than relying on a vendor’s stated accuracy figures.
- Adverse media integration. Some screening tools fold in adverse media checks; others treat it as a separate add-on. Know which you’re buying before you assume coverage.
- PEP list handling. Politically exposed persons screening has different false-positive dynamics than sanctions screening and deserves its own evaluation pass rather than being judged as part of the same score.
Sanctions screening tools tend to be judged almost entirely on precision, because the cost of a missed match is so much higher than the cost of a false positive. If a vendor can’t walk you through their matching logic in plain language, that’s worth treating as a signal.
Case management and SAR filing software that doesn’t bottleneck investigators
A strong detection engine feeding a weak case management system produces the same outcome as a weak detection engine: suspicious activity reports filed late, inconsistently, or not at all. This category gets less attention in buying decisions than it should, partly because it’s less visible in a product demo and more visible in the daily grind of an investigator’s queue.
Evaluate case management and SAR filing tools on:
- Workflow configurability. Can your team build escalation paths, assign cases by risk tier, and set SLAs without a vendor professional services engagement?
- Audit trail completeness. Examiners want to see not just the final disposition of a case but the full trail of what an investigator reviewed and when. A system that doesn’t log this automatically creates manual work later.
- Filing integration. Direct e-filing integration with FinCEN (or the relevant filing authority for your jurisdiction) saves meaningful investigator time compared to export-and-upload workflows.
- Case load visibility for managers. A compliance lead needs to see queue depth and aging in real time, not reconstruct it from spreadsheets at month end.
The bottleneck in most compliance teams isn’t detection volume, it’s investigation throughput. A case management tool that cuts the time to close a case by even a modest margin often has more operational impact than a marginal improvement in detection accuracy.
Where crypto-native AML tools fit, and where they don’t
Crypto-specific AML tools solve a problem that general-purpose transaction monitoring platforms generally can’t: tracing value across wallets, mixers, and chains where there’s no account number or routing number to anchor a rule. If your fintech touches crypto rails at all, even indirectly through a banking partner that custodies digital assets, this category deserves a separate line item in your evaluation rather than an assumption that your existing monitoring stack covers it.
Where crypto-native tools genuinely add value:
- Tracing fund flows across wallets and exchanges to assess counterparty risk before onboarding or processing
- Flagging exposure to mixers, darknet markets, and sanctioned wallet addresses
- Risk-scoring wallets at the point of deposit or withdrawal
Where they fall short: most crypto-native AML tools are not built to handle fiat transaction monitoring, SAR workflows, or sanctions screening against traditional watchlists. Treating a blockchain analytics tool as a full AML replacement for a fintech with meaningful fiat volume leaves gaps on both sides. For a deeper look at how this tracing actually works at the protocol level, the mechanics are covered in a piece on how regulators trace illicit crypto flows.
The practical approach for most fintechs with mixed fiat and crypto exposure is running a crypto-native tool alongside, not instead of, a traditional transaction monitoring platform, with case management as the layer that unifies alerts from both.
Matching tool categories to your transaction volume and risk profile
There’s no universal stack. The right combination of tools depends on volume, customer risk profile, and how much of your compliance function you’re building in-house versus outsourcing.
A rough way to think about it:
- Low volume, lower risk customer base (early-stage fintech, narrow product set): a combined transaction monitoring and sanctions screening platform with built-in case management may be sufficient, and the integration overhead of running separate best-in-category tools likely isn’t justified yet.
- High volume, standard risk profile (consumer payments, neobanking): separate best-in-category transaction monitoring and case management tools usually pay for themselves once alert volume climbs, because a bundled suite’s weaker component becomes the bottleneck.
- Any volume, elevated risk exposure (crypto-adjacent, cross-border remittance, high-risk merchant categories): expect to run a dedicated sanctions screening tool, a transaction monitoring platform tuned for your specific typologies, and crypto-native tooling if digital assets touch your flows anywhere.
Integration capacity matters as much as the tools themselves. A platform that’s technically superior but can’t connect cleanly to your KYC provider and core banking system will cost more in engineering time than the licensing difference between vendors ever saves. The same logic that applies to comparing KYC software providers across markets applies here: the integration surface is often the real decision point, not the feature comparison sheet.
Questions to ask before you commit to a vendor
Before any contract gets signed, get specific answers to:
- What’s the false positive rate at a transaction volume comparable to ours, not the vendor’s best reference client?
- How often do detection models retrain, and who controls that process?
- What does implementation actually take, in weeks, with our existing KYC and core banking stack?
- Can we export our data cleanly if we switch vendors later?
- What’s the audit trail for a regulator asking us to justify why a specific transaction was cleared or escalated?
- Who owns tuning after go-live, us or the vendor’s services team?
Vendor demos are built to answer the questions vendors want asked. The questions above are built to surface the ones that matter once the platform is running against your real data.
Before signing with any AML vendor, run them through the full vendor risk assessment checklist to make sure the decision holds up past the sales cycle.