
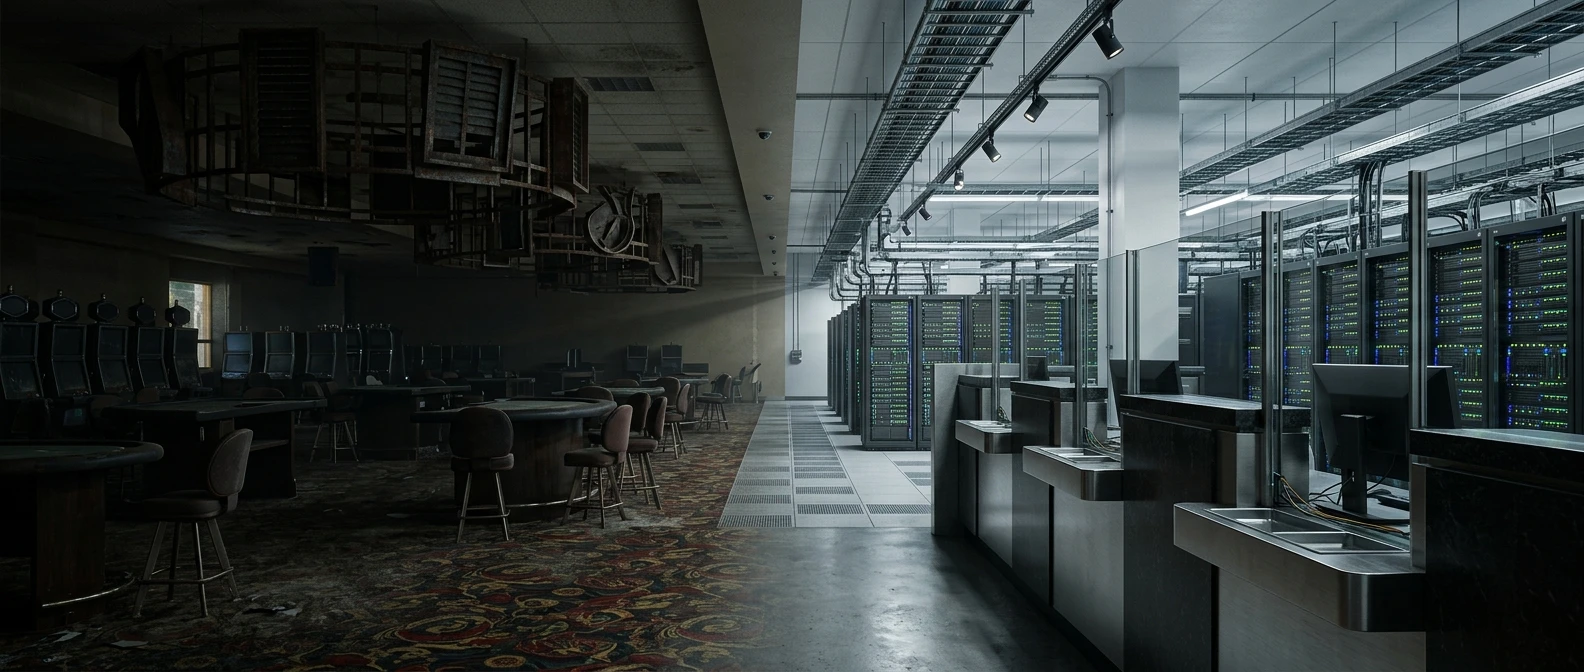
The DeFi of the yield farming era ran on incentives that could not last. Protocols printed governance tokens to attract deposits, deposits chased the highest annual percentage yield wherever it appeared, and the whole system reset every time the incentives dried up. That cycle has not disappeared entirely, but it no longer defines the space. The infrastructure being built in 2026 looks far more like financial plumbing than a casino floor, and the capital moving through it increasingly comes from institutions that would not have touched the sector five years ago.
This shift matters because it changes what DeFi is actually for. The early promise was permissionless access to financial services without a bank in the middle. The current build-out keeps that architecture but adds the compliance, custody, and settlement layers that let regulated money participate without breaking its own rules. Understanding where those pieces now sit is the difference between reading DeFi headlines and understanding what is actually happening underneath them.
From Yield Farming Hype to Institutional Plumbing
The protocols attracting serious capital in 2026 are not the ones offering the highest returns. They are the ones offering the most predictable ones. Lending markets, liquidity venues, and settlement layers are being evaluated on uptime, audit history, and counterparty risk, which are the same questions a treasury desk asks about any piece of financial infrastructure.
This is a function of who is now using these rails. Market makers, asset managers, and corporate treasuries do not need a token incentive to show up. They need a system that settles reliably and that they can explain to a compliance officer. The protocols that have survived into this phase of the market are the ones that rebuilt around that requirement rather than around token emissions.
The practical result is that total value locked, once a vanity metric inflated by circular incentive loops, is starting to mean something closer to what it claims to measure. Capital sitting in a lending pool or a liquidity venue today is more likely to be there because the yield reflects genuine borrowing demand or genuine market activity, not because a reward token is temporarily worth more than the risk.
Real World Asset Tokenization Becomes DeFi’s Biggest Growth Story
If one trend defines DeFi’s maturation this year, it is the tokenization of real world assets. Treasury bills, private credit, real estate, and corporate bonds are being issued as on-chain tokens that can be held, traded, and used as collateral inside DeFi protocols. This is not a side experiment anymore. It has become the largest source of new value entering the sector.
The appeal is straightforward. Tokenized treasuries give DeFi users exposure to yield backed by a real, low-volatility asset instead of yield manufactured by inflationary token rewards. For the institutions issuing these tokens, it offers a new distribution channel and a settlement process that can be faster and cheaper than the traditional custodial chain.
What makes this different from earlier attempts at asset tokenization is the plumbing now surrounding it. Pricing feeds, redemption mechanisms, and legal wrappers have matured to the point where a tokenized bond can be redeemed for its underlying asset in a way that holds up under scrutiny. That legal and operational seriousness is what separates this wave of real-world asset tokenization from the proof-of-concept pilots that came before it.
For readers who want the fuller picture of how these asset categories fit alongside the rest of the crypto landscape, the breakdown in Top Types Of Cryptocurrencies 2026 covers where tokenized assets sit next to the coins and tokens most people already recognize.
Regulatory Clarity Is Finally Shaping How Protocols Are Built
For most of DeFi’s history, protocols were designed first and regulation was something to react to afterward, often at considerable cost. That order has started to reverse. Developers are now building with specific regulatory frameworks in mind from the first line of code, because the cost of retrofitting compliance after launch has proven high enough that few teams want to repeat it.
This has produced a visible split in how protocols are architected. Some are built explicitly for open, permissionless participation and accept the limits that come with staying outside regulated markets. Others are built from the ground up to interface with licensed entities, which means identity checks, reporting requirements, and jurisdictional restrictions are part of the protocol design rather than an afterthought bolted on.
Neither approach is replacing the other. What has changed is that both now exist as deliberate choices rather than as one model slowly being forced to comply after the fact. That clarity, even where the rules themselves are still being finalized in various jurisdictions, has given builders enough certainty to design for a specific regulatory outcome instead of guessing.
Permissioned Pools and the Rise of Compliant DeFi
One of the more concrete outcomes of that regulatory clarity is the permissioned liquidity pool. These are pools that function like any other DeFi liquidity venue but restrict participation to wallets that have passed an identity or accreditation check. The mechanics underneath are the same automated market maker logic that powers open DeFi; the access layer is what differs.
This matters because it solves a problem that had kept institutional money on the sidelines. A bank or fund can participate in an on-chain pool without exposing itself to anonymous counterparties it cannot screen, while still getting the efficiency of smart contract settlement instead of a manual clearing process. The compliance sits at the gate rather than being impossible to achieve at all.
Compliant DeFi is not without its critics. Permissioned pools reintroduce a gatekeeper, which runs against the original permissionless ethos that drew many early users to the space. But for the purpose these pools now serve, moving regulated capital at scale, that tradeoff is the one making institutional participation possible in the first place.
Cross Chain Interoperability Ends the Era of Siloed Liquidity
DeFi spent years fragmented across chains that did not talk to each other well. Liquidity sat in isolated pools on separate networks, and moving assets between them meant routing through bridges that were, for a long stretch, the single most exploited piece of infrastructure in the entire crypto industry.
That fragmentation is being resolved less by any single winning blockchain and more by interoperability standards that let liquidity move securely across chains without users needing to understand the routing underneath. Settlement protocols built specifically for cross-chain messaging are replacing the ad hoc bridge contracts that caused so many of the earlier security failures.
The practical effect for users and institutions alike is that liquidity depth no longer depends on which chain an asset happens to live on. A tokenized treasury issued on one network can serve as collateral in a lending protocol on another without a manual, risk-laden transfer in between. That is a meaningful change from an industry that, until recently, treated each chain as its own separate economy.
Why Banks Are Quietly Building on DeFi Rails
Several major banks have begun piloting settlement and custody systems built on the same public blockchain infrastructure that retail DeFi protocols use, rather than building fully private, closed systems from scratch. The reasoning is practical: public chains already have the liquidity, tooling, and developer ecosystems that would take years and significant cost to replicate privately.
What banks are adopting is the rails, not the risk profile of early DeFi. They are running permissioned instances, using tokenized deposits instead of volatile crypto assets, and keeping custody and compliance firmly under their own control. But the settlement logic, the smart contract infrastructure, and in some cases the actual public blockchains underneath are the same ones retail users interact with directly.
This convergence is quiet by design. Few institutions want to publicize that their internal settlement pilot shares infrastructure with a protocol retail users also use to trade. But the direction is consistent enough across multiple major banks that it points to where institutional finance is placing its long-term infrastructure bets. For a deeper look at how this convergence is reshaping banking specifically, Impact Of Crypto On Banking goes further into what it means for the traditional banking sector as these rails get adopted more widely.
What a More Mature DeFi Means for Everyday Users
For individual users, this maturation shows up as fewer eye-catching returns and more durable ones. The protocols most worth paying attention to now are the ones with real revenue, real collateral, and real auditability, rather than the ones offering the largest token reward this week.
It also means more exposure to real-world asset yield without needing a brokerage account built for institutions. Tokenized treasuries and compliant pools are, in effect, opening parts of institutional finance to retail participants who previously had no direct access to them.
The tradeoff is that some of this maturing DeFi looks and behaves more like traditional finance, with identity checks, jurisdictional restrictions, and permissioned access replacing the fully open systems of DeFi’s early years. For users who valued that openness above all else, this will feel like a loss. For users who simply wanted reliable, transparent financial infrastructure, 2026’s defi trends represent the sector finally building toward that goal.
For a closer look at how these shifts are feeding into mainstream finance, read Impact Of Crypto On Banking next.